Published February 11, 2026 · 5 min read · Health Insurance
Episode 06 · Fredrick Insurance Brokers Podcast
Coverage is a strategy, not a product.
Health insurance should feel like a safety net, not a maze. Yet I meet people every week who feel overwhelmed, misled, or boxed into plans that never truly fit their lives. The traps are predictable — choosing the first plan that pops up online, assuming marketplace HMOs are the only option, or trusting a call center that focuses more on new sales than long-term service.
Coverage is a strategy, not a product. A good plan aligns networks, deductibles, and out-of-pocket limits with your doctors, medications, and tolerance for financial risk.
Here’s how I walk every client through it. 👇
Who Is Giving You Advice — And What Are Their Limits?
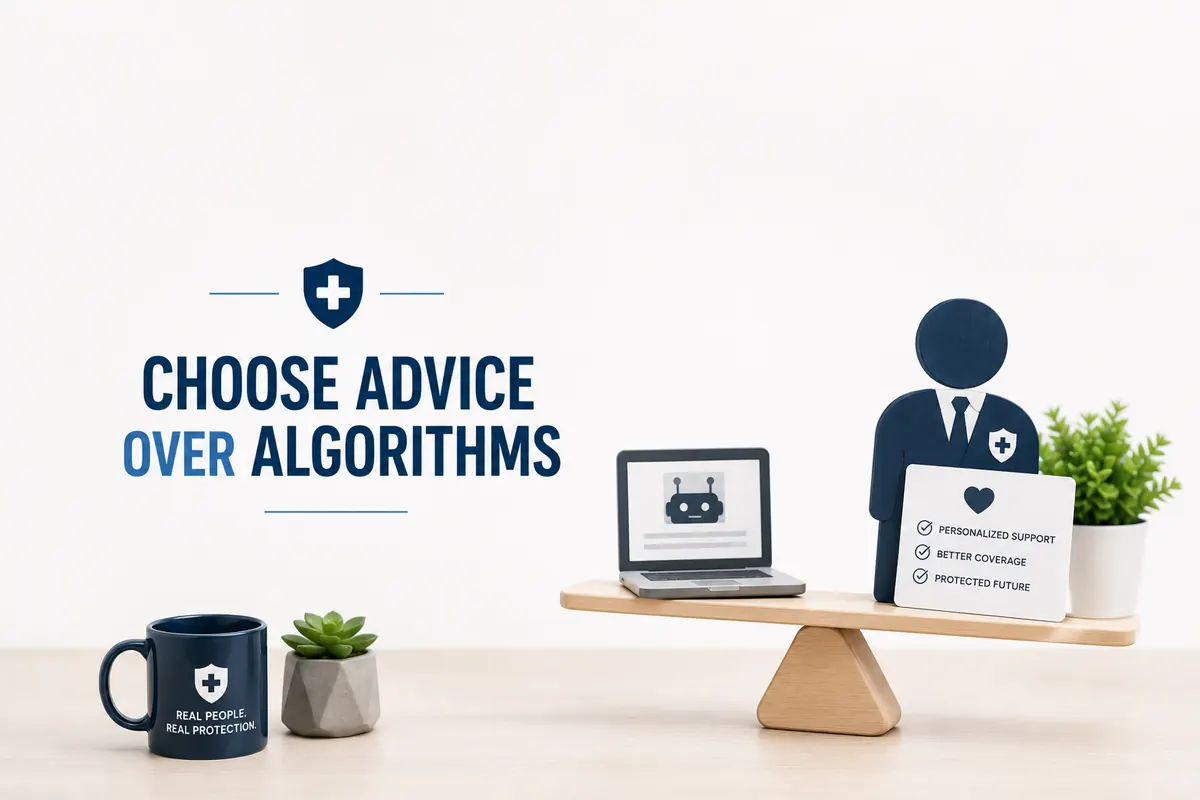
Captive agents represent one company. Many are kind and well-intentioned, but their toolbox is limited, which means your options are limited. Recommendations often lean toward what their carrier offers, not necessarily what fits your life.
As an independent broker, I work across multiple carriers and product types, which lets me match coverage to your doctors, travel patterns, and budget. Experience matters — the rules have changed dramatically since the ACA and continue to evolve.
Where the HMO vs PPO Divide Hurts Most
HMOs require referrals and often keep care within a tight system. That can work for routine needs but becomes restrictive when you need specialized care or a second opinion.
Marketplace plans are frequently HMOs or EPOs. Alternatives exist: private PPOs, level-funded group plans for small businesses, off-exchange plans in certain states, and indemnity/health-sharing structures with important caveats.
Where private PPO options often pull ahead:
Lead forms trigger a flood of calls because your information is sold — repeatedly.
Why DIY-ing It Online Backfires
Some callers sound confident but may be unlicensed or working under someone else’s license. Their goal is volume, not fit.
📞 Lead Form = Sold Lead
One form often gets resold to a dozen agents. Expect the call storm and the texts. Quality of advice varies wildly.
🤝 A Broker Knows Your File
When a claim is denied or a prescription is re-tiered mid-year, you want someone who can escalate with the carrier from your specific history.
🔁 Long-Term Retention is the Model
Brokers who build a long-term book succeed through retention. They’re incentivized to keep you satisfied year after year — not to close once.
If You’re Already in a Plan You Dislike, Change Is Usually Possible
Many individual plans allow cancellation at any time, though re-entry rules and special enrollment triggers matter. Small employers can switch servicing agents through an agent-of-record change without disrupting employee coverage.
A smooth transition requires planning: confirm effective dates, avoid gaps, transfer prescriptions, verify your providers in the new network before signing anything.
A 4-Step Plan You Can Use Today
Start with your must-keep doctors and hospitals
The network filter is non-negotiable. Build the plan around your providers, not the other way around.
List recurring medications and expected procedures
The formulary tier on your brand-name script changes your year more than the premium does.
Set an out-of-pocket ceiling you can absorb
A bad year shouldn’t destabilize your budget. Pick a max OOP you can live with.
Compare total cost of care, not just premium
Premium + deductible + likely copays + likely coinsurance + max OOP. Run both ways before you commit.
4 Questions To Ask Before You Decide
“Are you a captive agent or independent broker?”
This question reveals the size of the menu before you order.
“What happens when a claim is denied mid-year?”
A broker should be able to walk you through the appeals path before you sign.
“Can you compare a PPO option for me even if I’m on the marketplace today?”
If the answer is “no,” you’ve confirmed the agent is captive.
“If I change plans mid-year, how do you handle the transition?”
Good brokers walk through effective dates, prescription transfers, and provider verification.
Health insurance doesn’t need to be perfect to be powerful. It needs to be intentional — and supported by someone who picks up the phone.
Three Truths From This Episode
If You Take Three Things Away
Coverage is strategy, not a product
Align networks, deductibles, and OOP to your doctors and risk — not to a brochure.
Independence opens the menu
A captive agent shows you their carrier. An independent broker shows you the market.
Service is the long game
You want someone who answers the phone when a claim is denied in February.
Not Sure If Your Plan Fits?
Let’s Pressure-Test It Together
Bring your current plan summary, your prescriptions, and your doctors. We’ll line them up against the broader market and see what fits better — Texan to Texan.
Schedule a Free Consultation →
Educational content only. Fredrick Insurance Brokers is an independent licensed insurance agency. A licensed insurance professional can help you review your options. We do not guarantee approval, savings, benefits, claim outcomes, or coverage; specific situations vary by carrier, plan, and applicable terms.