Buying insurance is one of the most important steps you can take to protect the things — and people — you care about most. But here’s the part most people skip: the broker you choose matters as much as the policy you buy.
There’s no shortage of insurance options or providers out there — which makes the decision feel overwhelming. The right broker cuts through the noise, matches coverage to your actual situation, and stays with you long after you sign the paperwork. The wrong one hands you a policy and disappears.
Before you commit to anyone, ask these four questions — and know what a good answer looks like. 👇
“Are you an independent broker or a captive agent?”
This is the single most important question you can ask — and the answer determines everything else about the relationship. The difference between an independent broker and a captive agent is not subtle. It fundamentally shapes the options you’ll be offered and whose interests come first.
✅ Good Answer Sounds Like
“I’m an independent broker — I work with multiple carriers so I can find the best fit for your specific situation.”
⚠ Red Flag Sounds Like
“I specialize in [Company Name] products and can help you find the right plan within our lineup.”
Key insight: A captive agent isn’t a bad person — they can be extremely knowledgeable. But their knowledge stops at their company’s door. An independent broker’s loyalty has no ceiling and no company affiliation pulling it sideways.
“How long have you been an insurance professional?”
Experience isn’t everything — but in a field as nuanced as insurance, it speaks for itself. A seasoned broker has navigated real claims, real edge cases, and real client situations that no training course can replicate. They’ve seen what happens when coverage gaps go unnoticed, and they know how to close them.
That said — a newer agent isn’t automatically the wrong choice. What matters is whether they can demonstrate knowledge, show proof of results, and have strong mentorship or team support behind them.
What experience actually gives you:
✅ Good Answer Sounds Like
“I’ve been in the industry for X years. Here are a few examples of situations I’ve helped clients navigate — including some tricky claims.”
⚠ Red Flag Sounds Like
Vague deflection, an inability to name specific examples, or defensiveness about their experience level.
Experience speaks for itself — and a confident professional will let it do exactly that.
“What support do you offer after I sign up?”
Enrollment is not the finish line — it’s the starting line. The real value of a great broker shows up after you have a policy: when you have questions, when you need to file a claim, when something doesn’t go as expected, or when your life situation changes and your coverage needs to change with it.
A broker who vanishes after the sale is not a broker — they’re a salesperson. What you want is an ongoing advisor who is accessible, proactive, and genuinely invested in your outcomes.
✅ Good Answer Sounds Like
“I’m available to help with claims, answer questions, and do an annual review every year to make sure your coverage still works for you.”
⚠ Red Flag Sounds Like
“You’ll mostly deal with the carrier directly once you’re enrolled.” That’s a broker telling you the relationship ends at the sale.
“What other types of insurance do you offer?”
Even if you’re only shopping for health insurance right now, this question is a fast and reliable way to verify you’re working with a true independent broker. A captive agent can only sell their company’s products — so if they can’t name a diverse range of insurance types across multiple carriers, that tells you everything.
Beyond being a litmus test, the answer is also genuinely useful. An independent broker who handles multiple product categories can serve as a single trusted advisor across your entire insurance picture — now and as your life evolves.
Products a well-rounded independent broker may offer:
✅ Good Answer Sounds Like
“We work across health, dental, life, auto, and small business — across multiple carriers. Whatever you need, we can compare options.”
⚠ Red Flag Sounds Like
“We mainly focus on [one product type] through [one carrier].” Limited scope = limited options for you.
Key insight: Asking about product range isn’t just a verification check — it’s a window into a broker’s creativity, depth, and ability to find solutions you didn’t know existed. The broader their toolkit, the better equipped they are to serve you.
Your Cheat Sheet
The 4 Questions — At a Glance
“Independent broker or captive agent?”
You want: independent — works for you, not a single carrier
“How long have you been in insurance?”
You want: experience with proof, or strong mentorship backing them
“What support do you offer after I sign up?”
You want: claims help, annual reviews, and genuine accessibility
“What other products do you offer?”
You want: a broad range across multiple carriers — the wider, the better
How We Answer These Questions
Here’s Where Fredrick Insurance Brokers Stands
There is a lot gained from an open, candid conversation with your insurance broker. Don’t be afraid to ask hard questions — a great broker will welcome every single one of them.
Fredrick Insurance Brokers is an independent licensed insurance agency. We work with multiple carriers so you can compare options side by side — not limited to a single company’s plans.
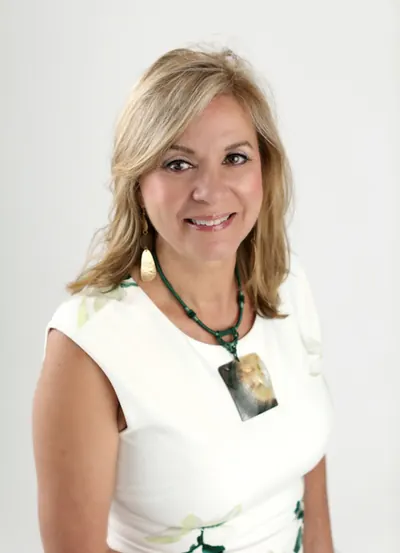
Katherine Clark is a licensed life insurance advisor and the founder of Fredrick Insurance Brokers. With a passion for helping individuals and families secure their financial future, she provides personalized guidance on health, life, and income protection plans. Katherine is committed to simplifying insurance decisions, ensuring her clients feel confident, informed, and protected every step of the way.