Health insurance is one of the most important financial decisions you’ll make — yet it’s one of the most misunderstood. Whether you get coverage through work, the marketplace, or a private plan, common myths can quietly cost you hundreds — sometimes thousands — of dollars every year.
As an independent brokerage serving North Texas, we hear these misconceptions constantly. Our job isn’t to sell you a plan — it’s to make sure you understand your options so you can choose what’s truly right for your situation.
Here are the 3 biggest health insurance myths we debunk every day — and what the truth actually looks like. 👇
“Once you sign up, you’re locked in for the entire year.”
This is one of the most common things we hear — and it stops people from exploring options that could save them real money mid-year.
While open enrollment is the main window for plan changes, it isn’t the only one. Qualifying life events — marriage, divorce, birth of a child, or loss of other coverage — open a Special Enrollment Period that lets you make changes outside the standard window. Certain adjustments to dependent coverage can often be made at any point during the year.
The assumption of rigidity prevents people from asking the questions that could improve their coverage and lower their costs.
Key insight: If you’ve had a major life change in the past 60 days, you may already qualify for a Special Enrollment Period — meaning you can switch or adjust your plan right now.
“The best health insurance always comes through your employer.”
This one has a grain of truth — for some people, employer-sponsored coverage is genuinely the best option. But the blanket assumption that it’s always the most cost-effective choice leads many healthy individuals and families to overpay without realizing it.
Here’s what most people don’t know: Group employer plans are priced using the collective health profile of the entire workforce. If your company has employees managing chronic conditions, requiring frequent specialist visits, or going through pregnancy — those costs are baked into everyone’s premiums, including yours.
For someone who is generally healthy and uses insurance minimally, a private individual plan may offer equivalent coverage at a meaningfully lower monthly cost.
Group plans are great for employees who use their insurance heavily. For healthy individuals, the premium math often tells a very different story.
Key insight: Never assume your employer plan is the best deal without comparing it to private market options. An independent broker can run a side-by-side comparison at no cost to you.
“My health insurance covers injuries that happen at work.”
This one surprises people — and it can have serious financial consequences. Most standard health insurance policies exclude or deny claims for injuries that occur in the workplace, because insurers expect workers’ compensation to handle those situations.
The problem: workers’ comp doesn’t always cover everything. And whether you receive workers’ comp has no bearing on what your health insurer is required to cover. A gap between them can leave you with significant out-of-pocket bills.
This especially affects:
Private individual health insurance sidesteps this entirely. Because it’s unconnected to your employment, it covers you wherever and whenever an injury or illness occurs — no employment context to complicate a claim.
Key insight: If you’re self-employed or have any physical element to your work, review your policy for workplace exclusions before you ever need to file a claim.
From Our Agency
Coverage Options Most People Don’t Know Exist
As an independent brokerage, we build plans around your specific situation — not a generic package. Here are three options that consistently surprise our clients.
Out-of-Pocket Protection
Chose a high-deductible plan? A supplemental policy covers that deductible when you need care — giving you low premiums with real protection.
Health Matching Account (HMA)
Like an HSA — but better. Funds never expire, can be used for elective procedures, and your balance doubles over time. Start sooner for greater benefit.
Maternity Coverage
Flat $250 co-pay for vaginal delivery, $500 for C-section — no surprise billing. Policy must be in place before pregnancy begins.
Free Consultation
Let’s Talk About Your Situation
This isn’t a sales call. It’s a direct conversation to understand your needs, compare your real options, and make sure you’re not leaving money on the table — or leaving yourself exposed. We may even confirm you’re already in great shape.
Schedule Your Free Call →📍 North Texas · (972) 375-0507 · Mon–Fri 9AM–5PM
Fredrick Insurance Brokers is an independent licensed insurance agency. We work with multiple carriers so you can compare options side by side — not limited to a single company’s plans.
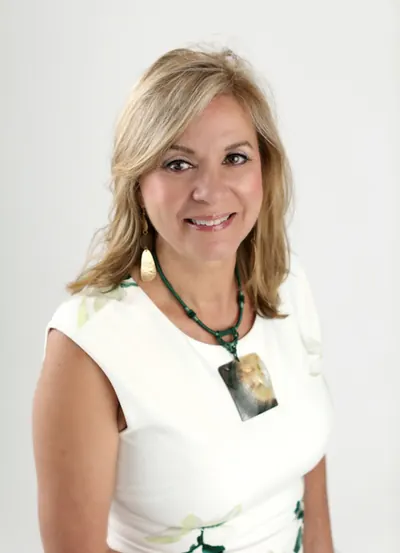
Katherine Clark is a licensed life insurance advisor and the founder of Fredrick Insurance Brokers. With a passion for helping individuals and families secure their financial future, she provides personalized guidance on health, life, and income protection plans. Katherine is committed to simplifying insurance decisions, ensuring her clients feel confident, informed, and protected every step of the way.