Short-term medical plans have exploded in popularity since the Affordable Care Act — and it’s easy to see why. The premiums are low, the sign-up is fast, and they feel like a smart stopgap when you’re between jobs, aging off a parent’s plan, or waiting for open enrollment.
But before you click “purchase,” there are serious limitations to these plans that most people don’t fully understand until it’s too late. At Fredrick Insurance Brokers, we educate every client on exactly what a short-term medical plan (STM) will — and won’t — cover before we ever let one walk out the door with it.
Here’s what you need to know. 👇
What Is a Short-Term Medical Plan?
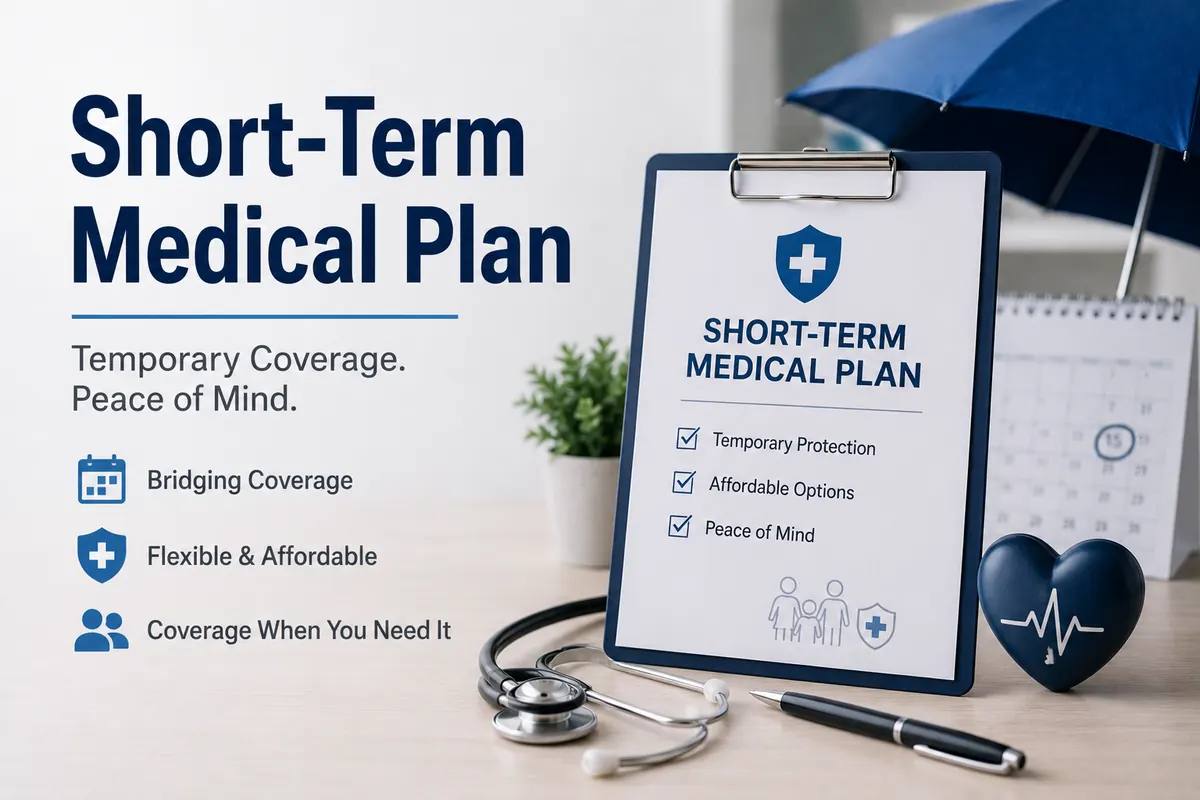
A short-term medical plan (STM) is a type of health coverage designed to fill temporary gaps — typically lasting up to 12 months. They’re not required to comply with the ACA’s consumer protections, which is exactly why they’re cheaper. And exactly why they can leave you dangerously exposed.
For generally healthy people who need absolutely no health services during that window, an STM might seem to work fine. But “works fine” is not the same as “protected.” The moment your health situation changes, the gaps become painfully clear.
Short-Term Medical Plans at a Glance
The Hidden Risks of Short-Term Coverage
The appeal of a lower premium is real. But the risks hiding underneath can far outweigh the monthly savings. Here’s what our brokers walk every client through before they consider an STM:
You Reset Every Single Year
Even plans marketed as “renewable” are still short-term. That means every 12 months, you’re treated as a brand-new applicant. Your deductibles reset. Your coverage history means nothing. You start from zero — every time.
Medical Events Become Pre-Existing Conditions
Say you have a health event in year one — a diagnosis, an injury, a procedure. When you go to renew your STM the following year, that event is now a pre-existing condition that may no longer be covered. A fully underwritten plan protects you from this. An STM does not.
Insurers Can Limit How Many Times You Renew
Most short-term health insurance companies can — and will — limit the number of consecutive times you can repurchase coverage. You could find yourself with no pathway back to coverage at all, especially if your health has changed during that period.
Out-of-Pocket Costs Can Be Devastating
The low premium feels like a win — until you actually need care. STMs often come with high deductibles, benefit caps, and exclusions that leave you paying the bulk of a serious medical bill yourself. The “savings” on premiums can evaporate with a single emergency room visit.
Planning a Family? Think Very Carefully.
STMs typically don’t cover maternity care. And because pregnancy is treated as a pre-existing condition for both parents in the STM world, starting or growing a family under short-term coverage could expose you to tens of thousands of dollars in uncovered costs.
What if you had a medical event in year one that wouldn’t be covered the following year — because it’s now a pre-existing condition? You need a plan that will not drop you.
Is a Short-Term Medical Plan Right for Me?
There’s no universal answer — which is exactly the point. The right coverage depends on your age, health history, family situation, financial cushion, and what you’re using insurance for. A healthy 28-year-old between jobs has a very different risk profile than a 45-year-old with young children and a family history of chronic illness.
At Fredrick Insurance Brokers, our commitment is education first. There is no perfect plan — if there were, none of us could afford it. But there are options that provide genuine value: first-dollar coverage from day one, protection that doesn’t drop you after a medical event, and plans you can keep until you’re 65 — at which point we’ll find you the best Medicare Supplement available.
Key insight: Contact us before you purchase a short-term medical plan. We’ll show you the coverage and rate differences side by side — no strings attached. You don’t know what you don’t know, and that’s exactly what we’re here for.
When Might a Short-Term Plan Actually Make Sense?
We believe in honest education — not fear tactics. There are narrow scenarios where an STM could be a reasonable bridge. Generally, that means all of the following are true:
If even one of those conditions doesn’t apply, we strongly encourage you to explore alternatives before committing to a short-term plan. The conversation costs nothing.
Our Commitment
We Educate Before We Recommend
Fredrick Insurance Brokers are committed to educating and empowering every client. We won’t let you walk out the door with a plan that doesn’t serve you — even if it’s the one you came in asking for.
Ultimately, the decision is yours. But you don’t know what you don’t know. Our job is to make sure you’re equipped to make the right call — and that if something happens, your plan actually has your back.
Fredrick Insurance Brokers is an independent licensed insurance agency. We work with multiple carriers so you can compare options side by side — not limited to a single company’s plans.
Katherine Clark is a licensed life insurance advisor and the founder of Fredrick Insurance Brokers. With a passion for helping individuals and families secure their financial future, she provides personalized guidance on health, life, and income protection plans. Katherine is committed to simplifying insurance decisions, ensuring her clients feel confident, informed, and protected every step of the way.