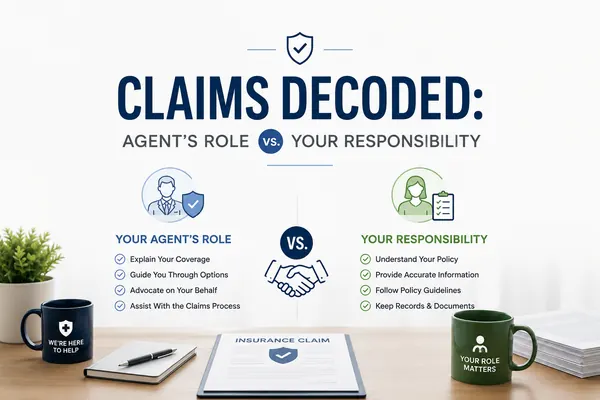
Health insurance often feels overwhelming because the rules keep shifting while our personal needs rarely fit into neat boxes. Over the years, I’ve learned that this tension is exactly where an experienced broker can make a difference — translating complexity into choices that match real life.
Here’s how I think about it after years on both sides of the changes. 👇
How the Landscape Has Changed
My journey in this field began before the Affordable Care Act, when plan designs offered wide variety and bundling options were common. Those early years taught me the importance of analysis: mapping pre-existing conditions, balancing deductibles with networks, and weighing premiums against realistic usage.
That mindset still matters today, but the landscape has changed. Regulations, dependent coverage through age 26, and network consolidation have reshaped what “choice” really means. Success now comes from precision — choosing what you will actually use rather than chasing theoretical benefits.
Advocacy at the Heart of the Work
At the heart of my work is advocacy. Many people age off a parent’s plan with little knowledge of networks, formularies, or how deductibles interact with out-of-pocket maximums. I believe that an expert who studies the market daily can compress hours of confusion into minutes of clarity.
The value is not just in picking a policy; it is in aligning coverage with care patterns, prescriptions, and cash flow. I often build layered solutions that pair core medical with ancillary coverage — dental, vision, accident, or critical illness — when the math supports it. Just as importantly, it respects personal values: preferred doctors, faith-based alternatives some clients consider, and the comfort of knowing a plan works where life actually happens.
What advocacy can look like:
Trust, Referrals, and Staying Current
Trust drives growth more than advertising ever could. My family business thrives on referrals from churches, local networks, and small business communities where reputation travels quickly. That circle sustains accountability — and it shapes everything I do.
🤝 A Family Business Built on Referrals
Reputation travels fast in churches, local groups, and small business communities. We grow because our clients trust us — and they trust us because we earn it one conversation at a time.
📞 Accountable When You Call
When a client calls with a claim issue, I answer. Even in conversations about life balance — whether it’s pickleball or gardening — the theme always returns to service.
📚 Always Current on the Rules
Advocacy means staying current on subsidy thresholds, special enrollment triggers, and evolving network rules. It also means explaining what not to buy — a lean bronze plan can be smart for a healthy self-employed client, while a family managing a chronic condition may choose richer coverage to avoid pharmacy shocks.
Education Is the Quiet Superpower
Education is the quiet superpower in this work. Here’s the simple sequence I walk every client through — the same one I use myself.
Start with your doctors and medications
List the providers and prescriptions you actually use. This single step rules out plans that look great on paper but quietly leave your favorite clinic out of network.
Filter by network, total cost, and flexibility
Cross-check your list against each plan’s network and formulary, then weigh the full-year cost (premiums plus likely out-of-pocket) and how the plan flexes if life shifts.
Document your non-negotiables and your “nice-to-haves”
Write down what must be covered (a specialist, a pediatrician, a specific medication) and what would simply be nice. The list becomes your compass when the brochures start to blur.
Price the real year, not the ideal one
If you expect two specialist visits and brand-name refills, model them before you enroll. A plan priced against the year you’ll likely have is almost always the smarter pick.
4 Questions To Ask Yourself Before Enrolling
“Which doctors do I need to keep in-network?”
Bring the names. Networks are the single biggest source of surprise bills.
“What prescriptions am I taking, and what tier are they on?”
Formularies vary widely. A plan that covers your brand-name refill at tier 2 instead of tier 4 can change your year.
“What two or three healthcare events am I likely to have this year?”
A planned procedure, a specialist visit, a new baby. Pricing the realistic year beats pricing the ideal one.
“What is my honest budget for both premiums AND surprises?”
A plan’s out-of-pocket maximum is the number that matters when something unexpected happens.
Three Quiet Truths From This Episode
If You Take Three Things Away
Precision beats theory
Choose what you will actually use, not what looks generous on paper.
Advocacy is the value
A broker’s job is not picking a policy — it’s aligning coverage with how you actually live.
A five-minute call is rarely wasted
It can reveal eligibility for assistance, a better network fit, or a cleaner claims path.
Filed Under
Educational content only. Fredrick Insurance Brokers is an independent licensed insurance agency. A licensed insurance professional can help you review your options. We do not guarantee approval, savings, benefits, claim outcomes, or coverage; coverage depends on each individual’s situation and the carrier’s underwriting and terms.